Просмотр новости
Найдите то, что Вас интересует
 Спутники
 РН
 SpaceX
 Роскосмос
 NASA
СпутникиРНSpaceXРоскосмосNASASixteen states provide Child Tax Credits to reduce poverty, boost economic security, and invest in children. State lawmakers have several options to maximize the impact of Child Tax Credits.
Child Tax Credits (CTCs) are effective tools to bolster the economic security of low- and middle-income families and position the next generation for success. When designed well, they build on the powerful base of the federal CTC, counteract some of its deficiencies, and lead to meaningful reductions in child poverty and deep poverty.1
More state lawmakers are choosing to help families in this way: for the 2027 tax year, 16 states will provide Child Tax Credits, many of which are targeted to those who most need them and refundable so children in the lowest-income families receive the full benefits. Together these credits constitute an annual multibillion-dollar investment in the next generation. As more states consider creating or strengthening these credits, lawmakers should design them for maximum impact.
Child Tax Credits: A Critical Tool to Help Families Make Ends MeetRefundable Child Tax Credits boost the after-tax incomes of qualifying families and offset some of the costs of raising children. These policies are especially important for the economic security and stability of lower-income families, helping them avert unexpected hardship that can threaten basic needs like housing, food, and utilities. Child Tax Credits are associated with reduced poverty, higher financial and household stability, improved child and maternal health, better educational achievement, stronger future economic outcomes, and more.2 These benefits are stronger with well-designed credits.
CTCs help families of all races. The largest share of recipients are white children. When designed well, these credits are particularly helpful to the lowest-income families and can ease challenges that hurt poor children and – because of discrimination and other factors – disproportionately harm children in Black, Hispanic, and Indigenous communities.3 Economic inequality, low wages, and child poverty are defining challenges in the U.S. CTCs help address these challenges.
Recent changes to the federal CTC boosted the credit from $2,000 to $2,200 for each eligible dependent under the age of 17. The credit is now also indexed to inflation. It phases out for married couples with incomes above $400,000 and for unmarried parents with incomes exceeding $200,000.
While these changes will move more money to families,4 lawmakers failed to address a major flaw in the CTC’s design that prevents many low-income families from receiving the full credit. This means low-income households can only receive $1,700 per child as a refund. Children whose parents or guardians are deemed “too poor”, earning less than $2,500, remain ineligible.
Meanwhile, changes to the federal CTC in 2017 required children to have a Social Security Number to receive the credit, denying 1.3 million children the credit who were previously eligible. Recent federal changes go even further, requiring at least one parent to have a Social Security Number, keeping the CTC from an additional 2.7 million children.5
In effect, the federal CTC maintains a trapezoid-like structure where some children are in families too poor to receive any credit, some fall within the phase-in range, some benefit from the full credit, some fall within the phase-out range, and some children do not receive the credit because their families have incomes that exceed the phaseout.
Figure 1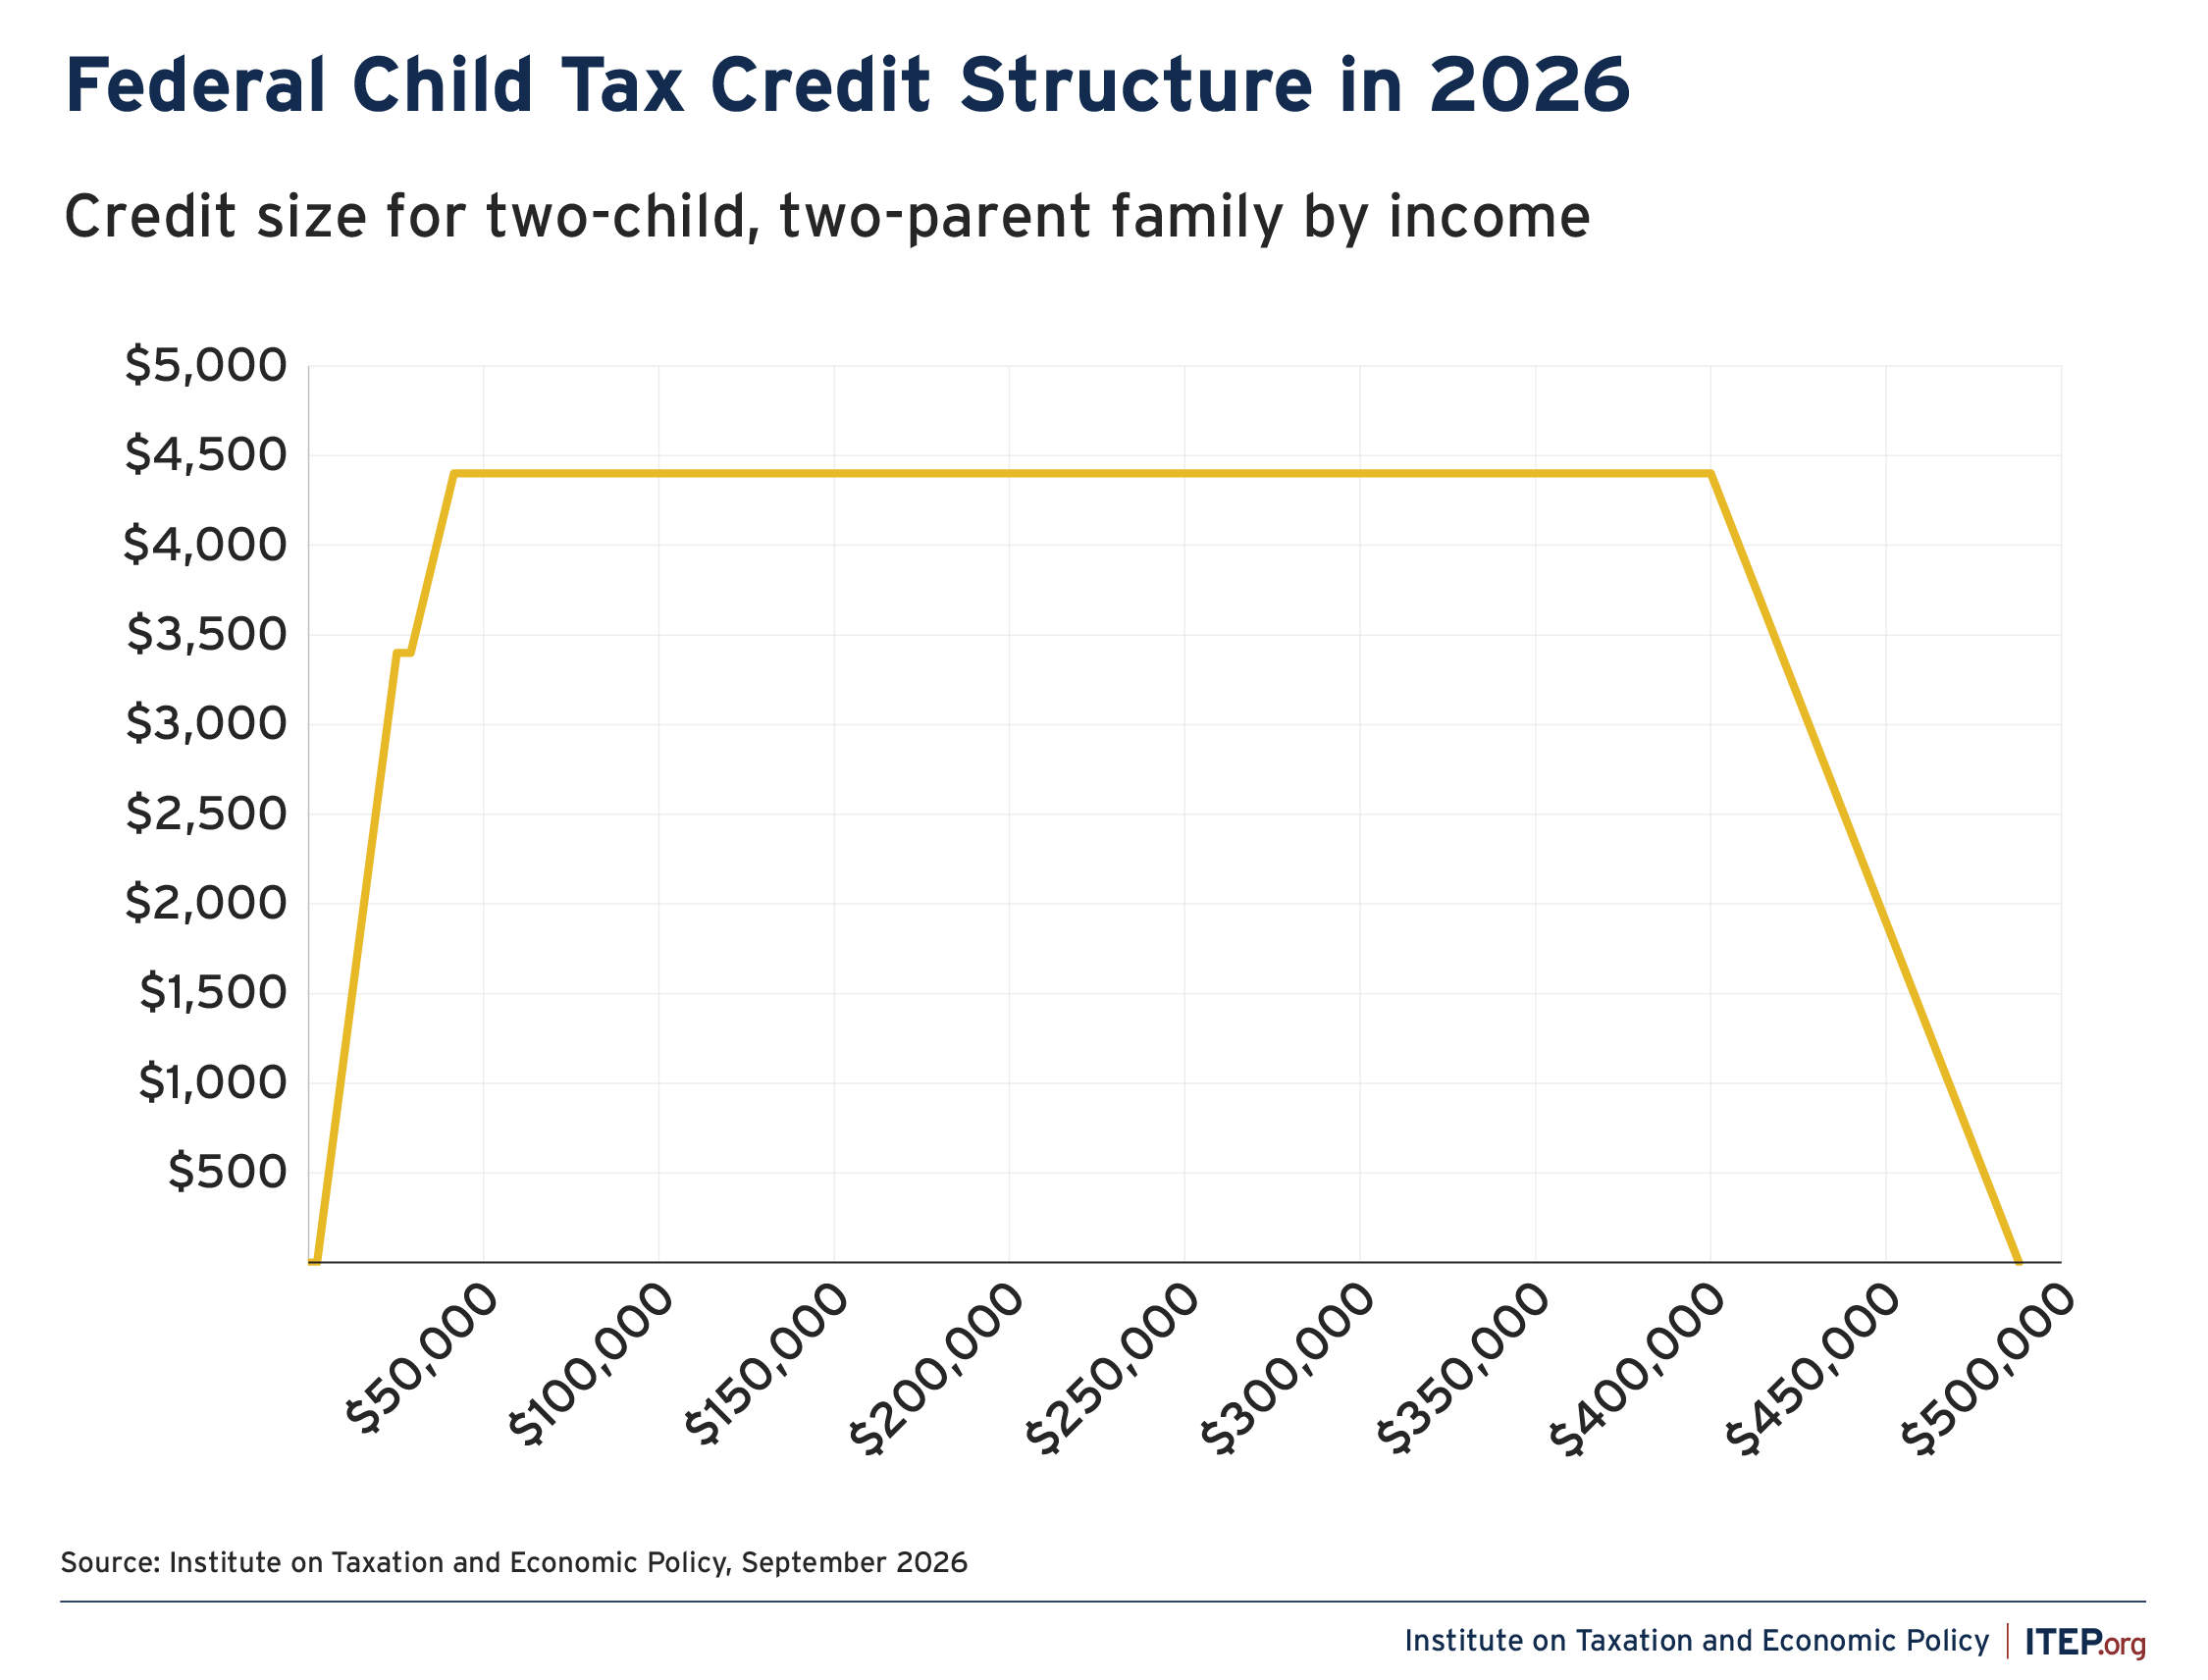
Since its enactment in the late 1990s, the federal CTC has grown and changed. For instance, the 2017 tax law increased the credit from $1,000 to $2,000 per child through 2025, reshaped it to allow more affluent families to claim it, and began excluding immigrant children without Social Security Numbers.6 Before this, all children whose parents met the income eligibility requirements, regardless of citizenship status, received the federal credit.
The American Rescue Plan Act of 2021 (ARPA) temporarily expanded the credit—for 2021 only—to $3,000 for older children and $3,600 for children under 5. It was also reformed to allow monthly credit payments rather than one annual lump sum. Most importantly, it was reworked to reach more children, including nearly one-third of children who live in families too poor to qualify for the credit under permanent law. In 2022, after the credit expansion expired, 45 percent of Black children, 42 percent of Hispanic children, and 23 percent of white children were no longer able to receive the full credit.7 Current limits for lower-income families disproportionately leave out children of color.
The expanded version of the federal CTC in effect for 2021 was wildly successful in reducing child poverty, cutting it by 46 percent. It lifted 3.7 million children out of poverty before it was allowed to lapse in 2022.8 Research has since shown that low and middle-income households overwhelmingly spent this boosted credit on housing, food, and clothing – a testament to how vital an expanded CTC is to helping families make ends meet each month.9 In the absence of federal action to reinstate those reforms, state lawmakers are creating and expanding Child Tax Credits to boost income and opportunities for children and families in their states.
The 2025 federal tax and spending law expanded the Child Tax Credit but took few lessons from the success of ARPA. While the credit amount was increased and indexed to inflation, the bill limited access to immigrant families and did nothing to improve refundability, meaning children whose parents and guardians earn low wages or are unable to work full time are denied the full benefit of the credit.
More States Are Adopting and Expanding Child Tax CreditsState lawmakers continue to adopt and expand state Child Tax Credits. Looking ahead to 2027, 16 states will provide these credits to children in their states.
Figure 2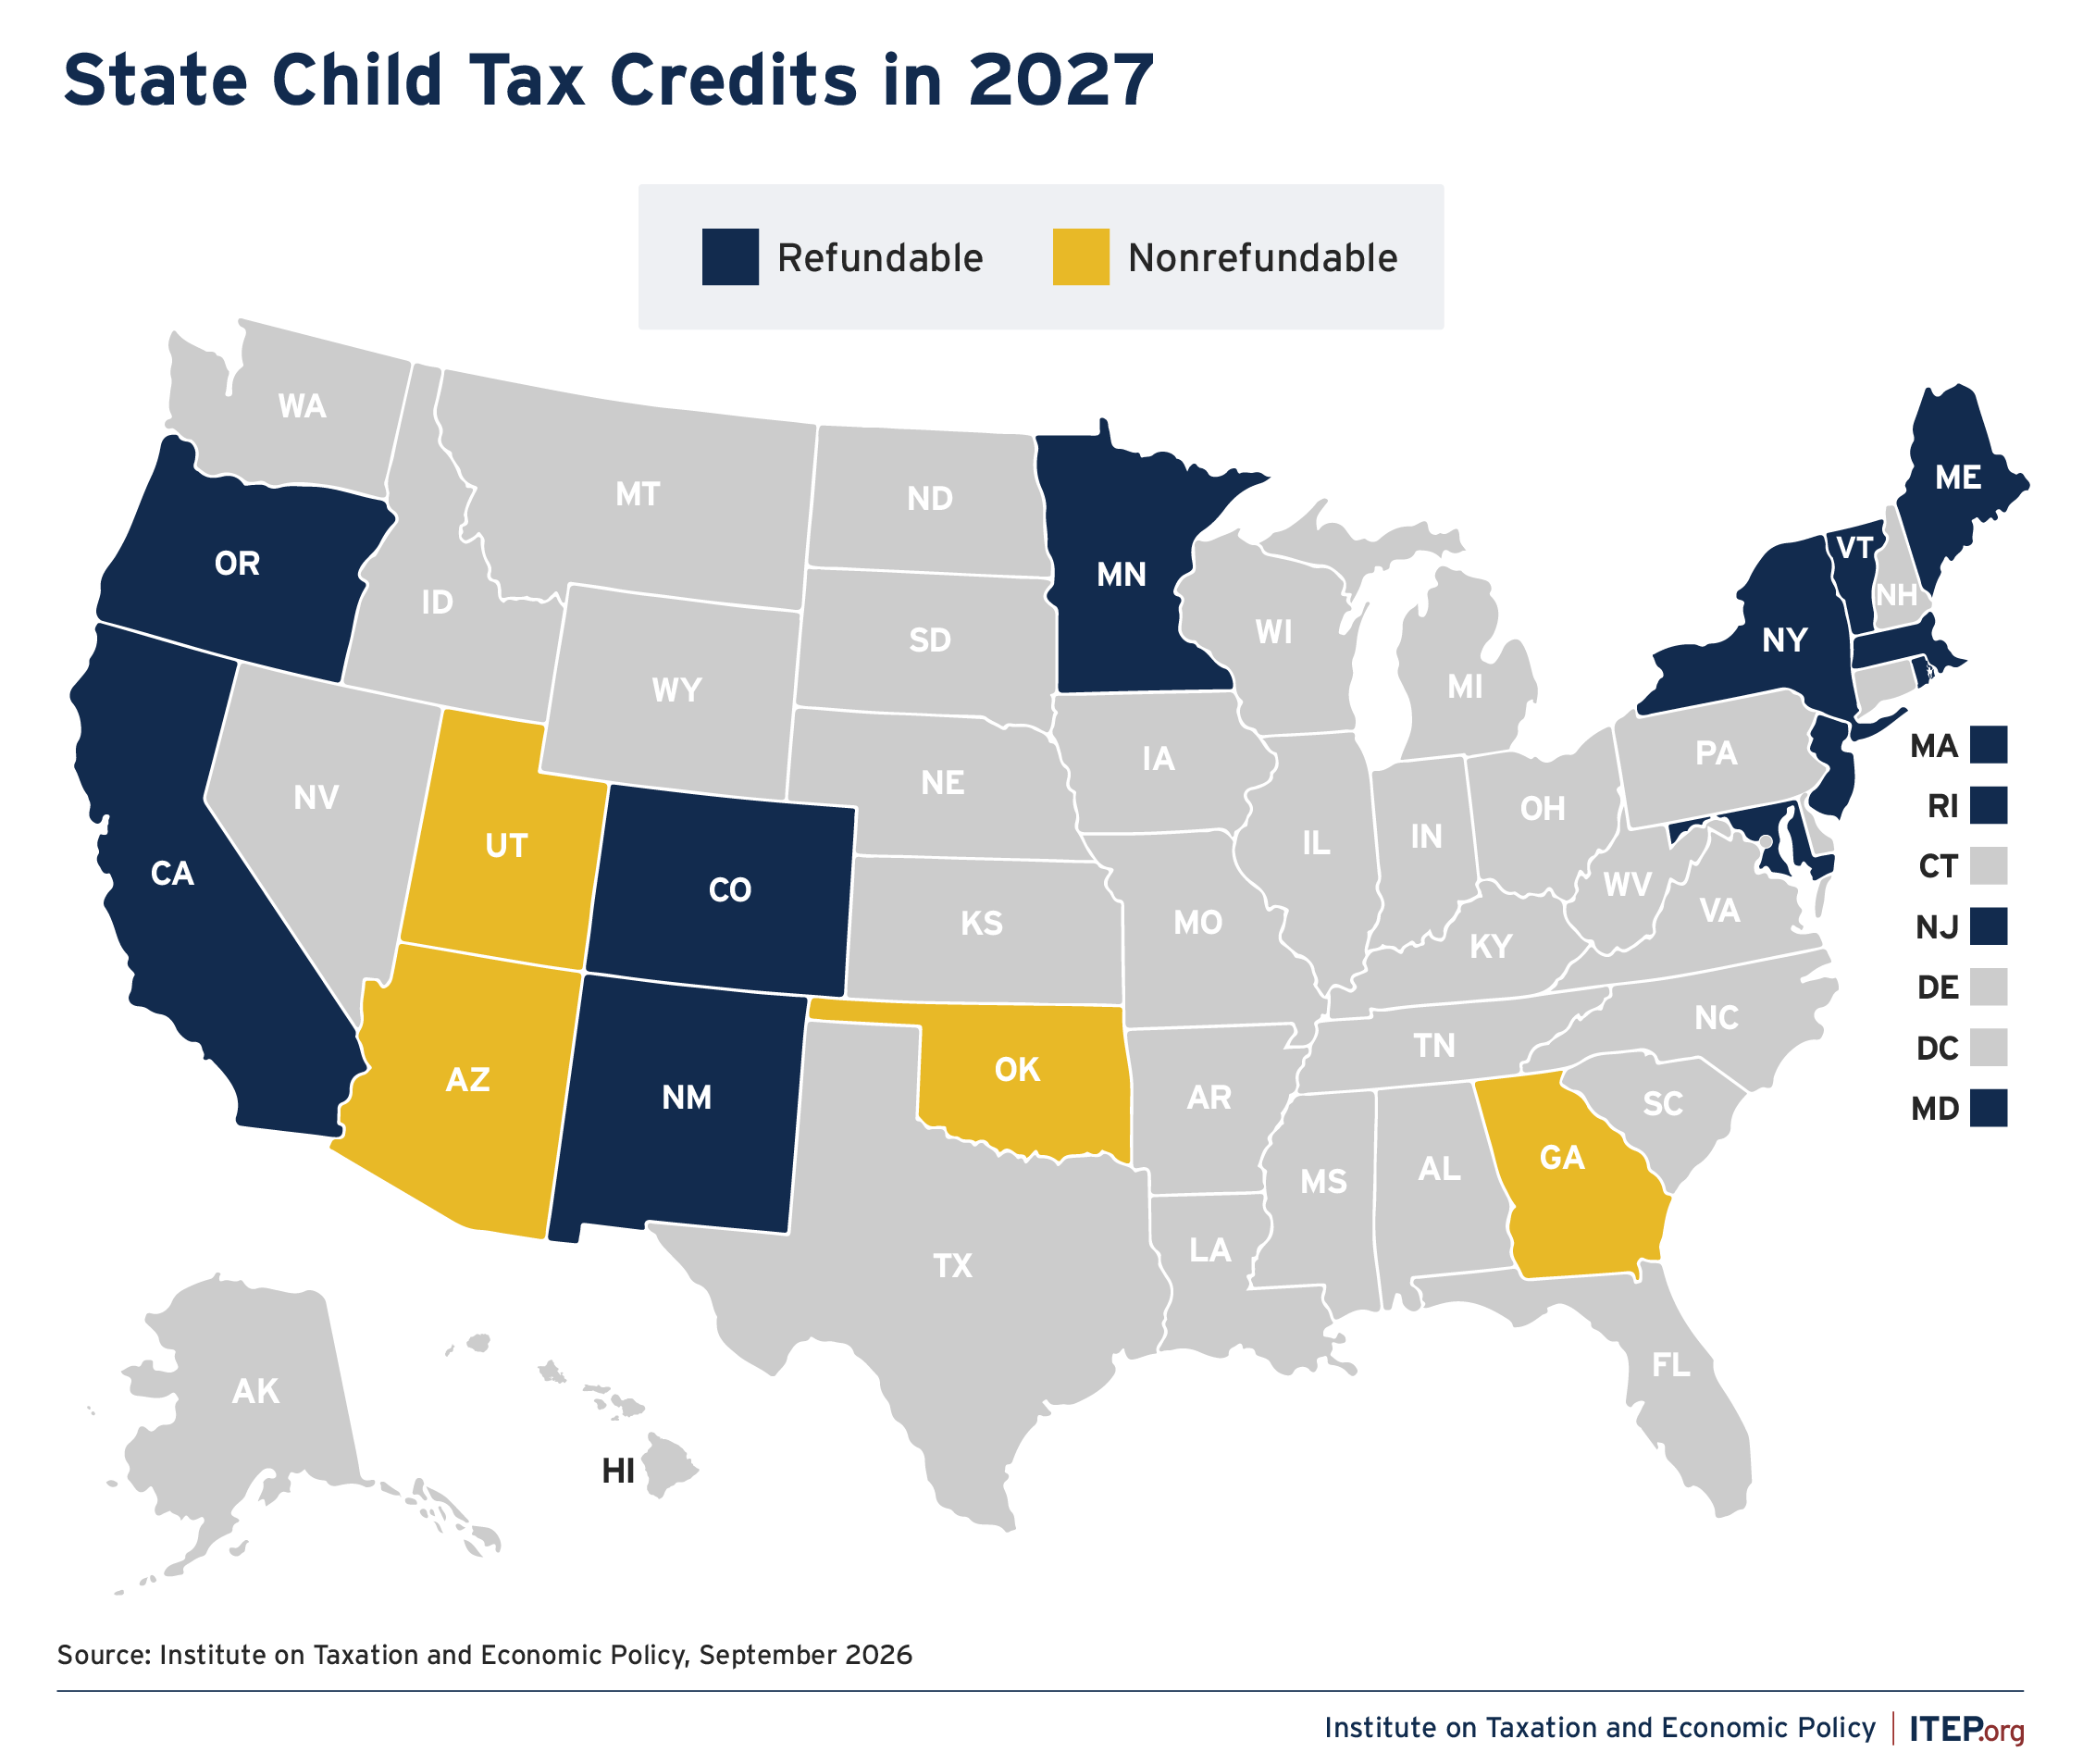
This year alone, lawmakers in four states created new or expanded existing Child Tax Credits. Lawmakers in Rhode Island passed its first refundable CTC while New Jersey lawmakers improved their existing refundable credit. In Arizona and Utah, lawmakers expanded their existing nonrefundable CTCs.10
Meanwhile, one major CTC expansion remains uncertain.
The District of Columbia was poised to enact its first Child Tax Credit of $1,000 per child under 18 in Tax Year 2025. This was possible because lawmakers passed legislation in February 2026 decoupling from multiple provisions in the 2025 federal tax law, thereby raising enough revenue to pay for the CTC. But Congress got in the way. Federal lawmakers tried to override the District’s law, although many observers note that Congress failed to act within the required timeframe. The legal uncertainty, in addition to slow local revenue collections, kept D.C. lawmakers from following through on debuting the new CTC.
Figure 3As lawmakers continue to deal with the fallout of the new federal tax and spending law, and in some cases steep and consistent state level tax cuts, some will look to cut existing programs and credits that are designed to help children and families. States should avoid removing policies that benefit those most likely to be harmed by economic uncertainty. State CTCs play an important role in state tax policy and complement broader efforts to support children and families, reduce poverty, and raise incomes of low- and middle-income families.
Figure 4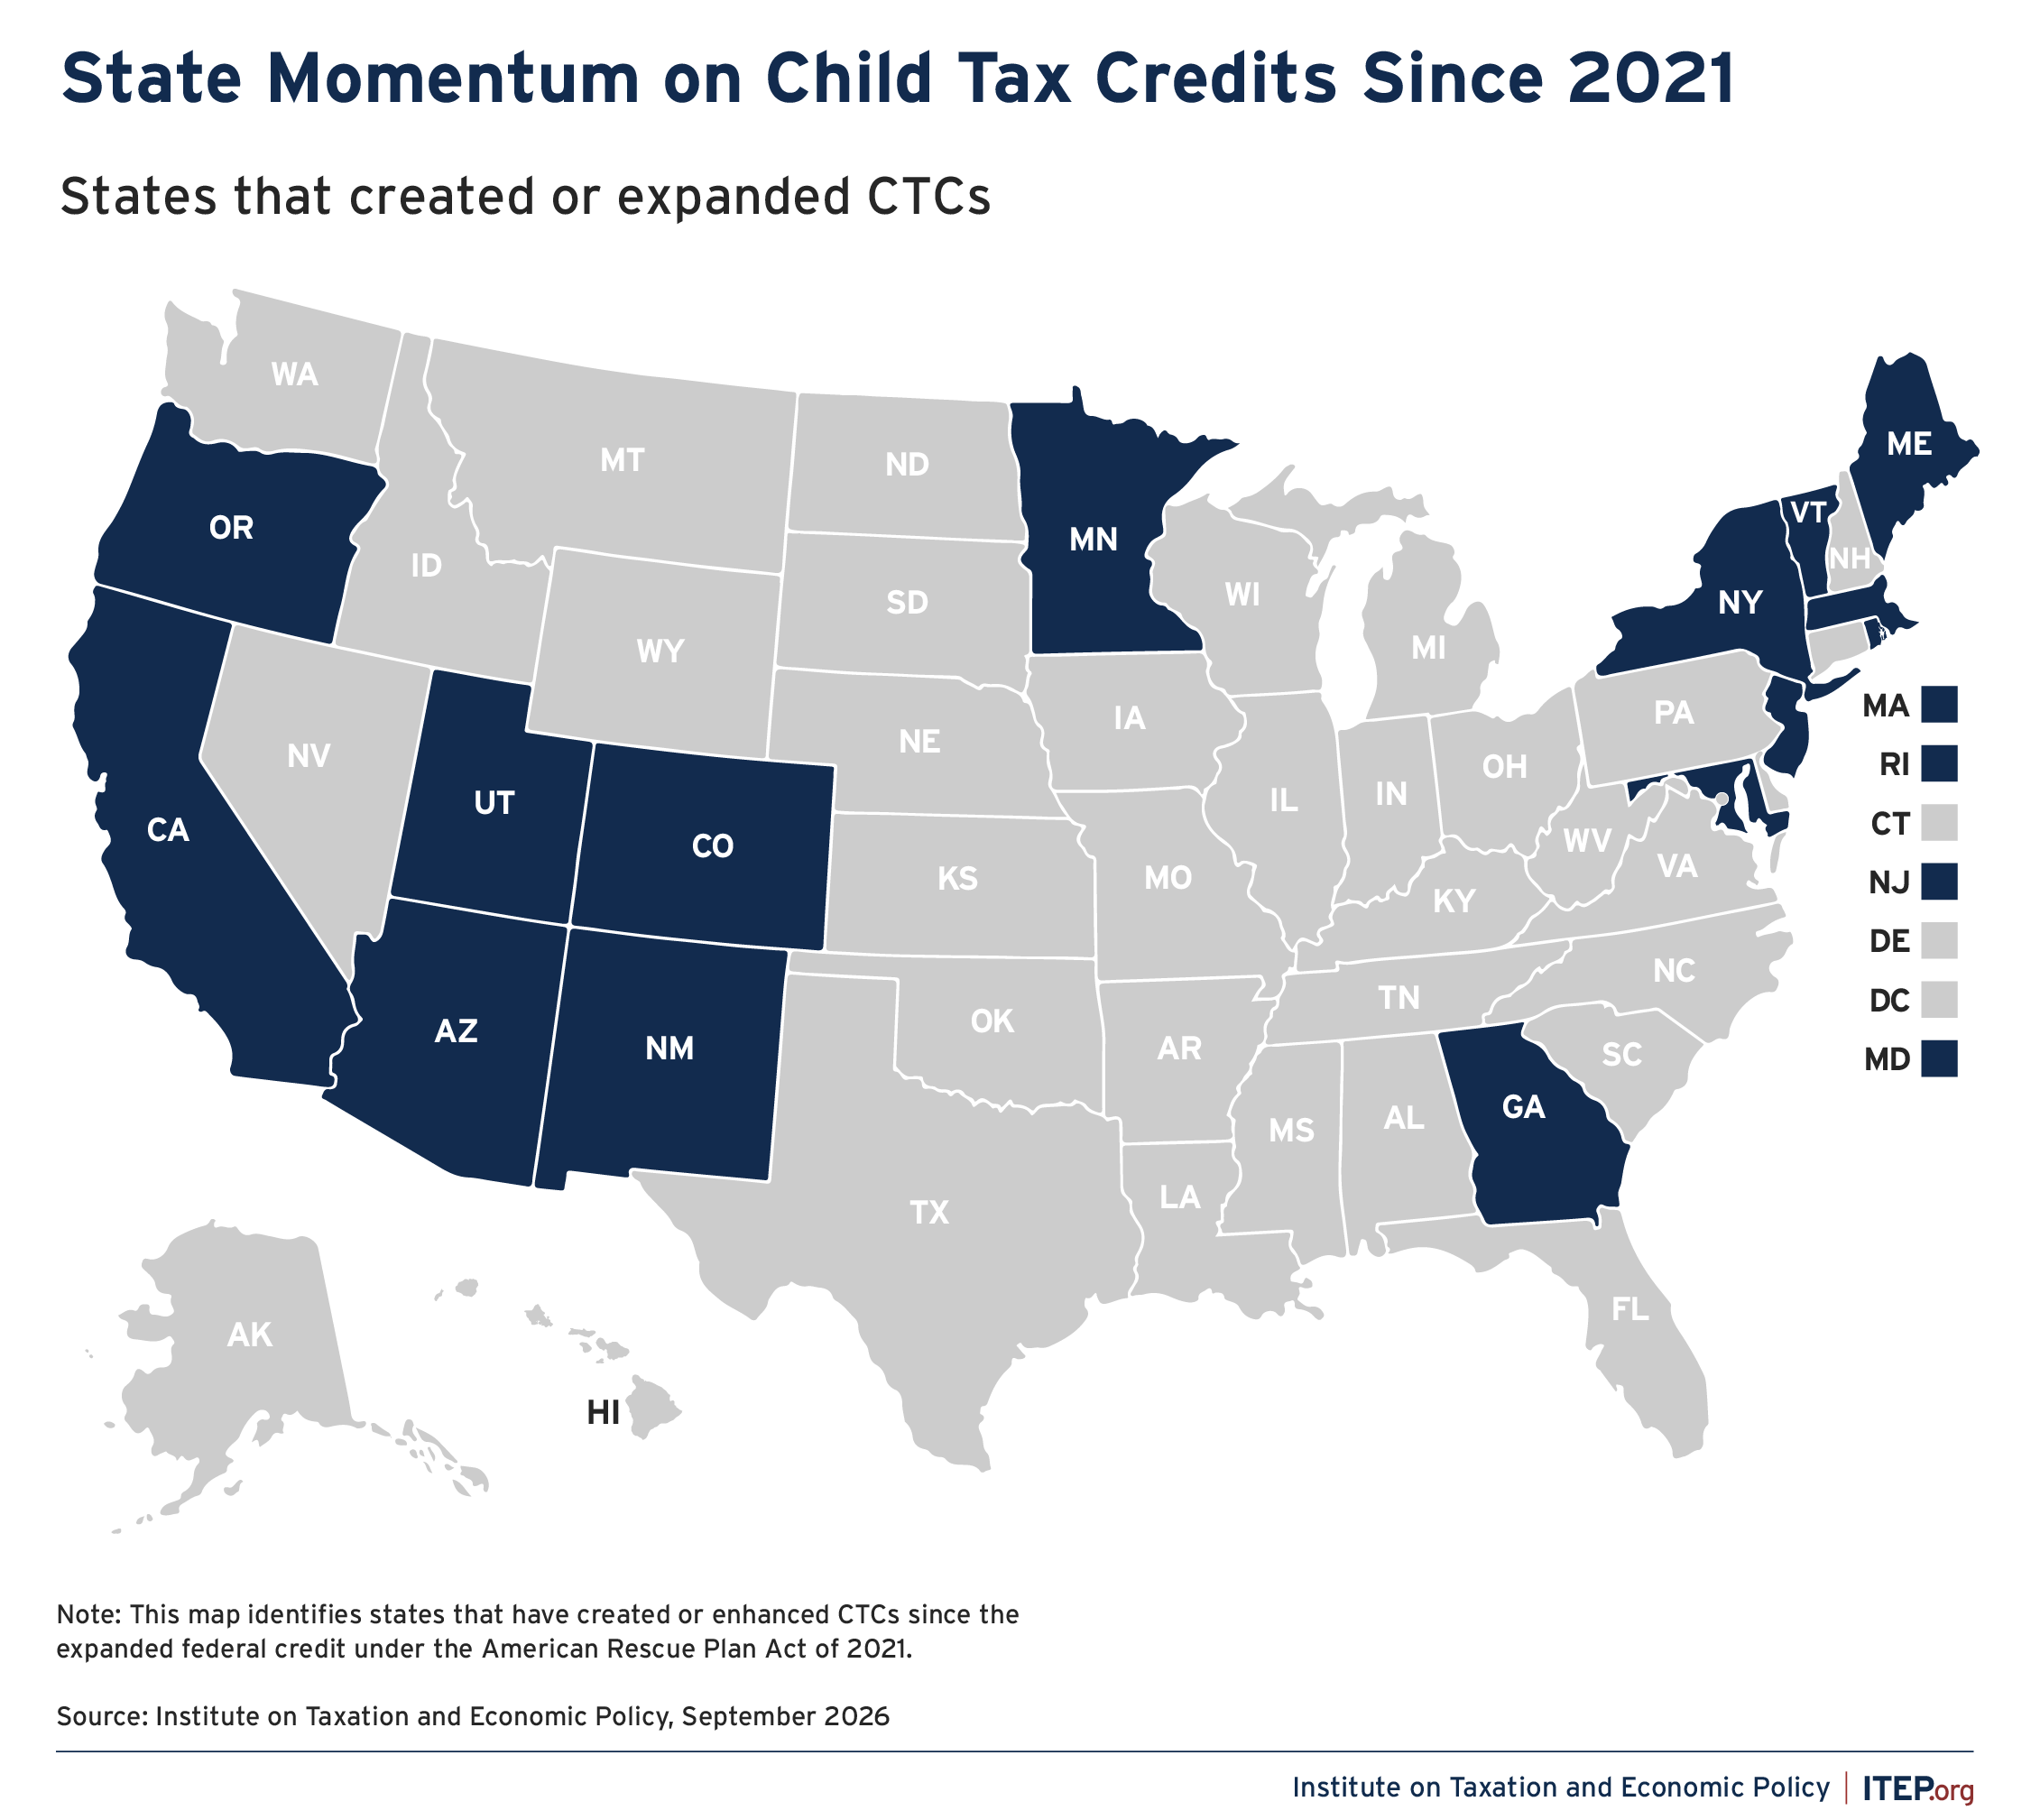
While most states have created CTCs that are independent of the federal Child Tax Credit, Oklahoma’s credit remains a nonrefundable credit worth 5 percent of the federal CTC or 20 percent of the federal Child and Dependent Care Credit.12 Ultimately, the nonrefundable nature of the credit means it cannot be used by lower-income families who have little state income tax liability but pay substantial amounts of sales, excise, and property taxes.
Given its connection to the federal credit, Oklahoma’s CTC is uniquely exposed to the whims of our federal lawmakers. For instance, new regulations from the U.S. Treasury could remove certain immigrant groups from claiming the refundable portion of the federal CTC, which could impact the amount able to be claimed at the state level for those groups in Oklahoma.
States Should Design Child Tax Credits With Equity in MindThe lapse of 2021’s federal Child Tax Credit enhancements has inspired a string of state actions and should continue to do so going forward. In the absence of additional action by Congress, states have several options to strengthen economic security and child wellbeing through new or expanded CTCs. Lawmakers should design these state CTCs with an eye toward equity by ensuring that the credit reaches as many low- and moderate-income children as possible.
1. Ideally, lawmakers should create standalone refundable CTCs where children benefit regardless of their family’s employment or immigration status.The advantage of implementing a credit separate from the federal CTC is that states can avoid the shortcomings of the federal credit (particularly the earnings requirement and lack of full refundability) that keep many lower-income families from receiving the full benefit. Instead, states can use their flexibility to determine the scope and scale of their credits without these restrictions.
That flexibility allows state lawmakers to:
States can piggyback CTCs on top of federal rules at a flat percentage rate, as many do with their EITCs. For example, a state CTC calculated as 10 percent of the federal CTC would amount to a $220 state credit in 2026 for any child who receives it in full. This offers a relatively simple template for states but has significant drawbacks including the relatively high income thresholds for eligibility.
The worst feature of the federal CTC is that children in many families are deemed too poor to receive the full benefit. Even if state lawmakers choose to conform to the federal CTC broadly, they should take care not to amplify this inequity and should establish a minimum, refundable benefit for lower-income families.
3. Lawmakers could also opt to fill the gap for children left behind by the federal CTC.State lawmakers can make up for the main shortcoming of the federal CTC by ensuring that children in families too poor to receive the full federal credit are brought up to the full $2,200 amount, or to some portion of that amount. This ensures that a state’s lowest-income children are not left behind. Of these three options, this is the most carefully tailored to reach only those families in the most vulnerable economic circumstances. As a result of its narrower reach, this option could also cost less than the other proposals, which may be appealing to some lawmakers concerned about the budgetary impact of more expansive CTC proposals.
Under any of these options, states should explore advanced or monthly payments in addition to annual payments. Recent federal experience suggests that this approach can play a role in meaningfully reducing child poverty, improving economic security, and enhancing families’ ability to meet their basic needs.17
| # | Наименование новости | Тональность | Информативность | Дата публикации |
|---|---|---|---|---|
| 1 | State Earned Income Tax Credits Will Support Families and Workers in 2027 | 0 | 10.77 | 15-09-2026 |
| 2 | State Action on Child Tax Credits and Earned Income Tax Credits Since 2021 | 0 | 5.6 | 27-08-2026 |
| 3 | The Child Tax Credit Leaves Out Millions of Children in 2026. There Are Better Alternatives. | 0 | 9.38 | 10-03-2026 |
| 4 | New tax credit adds planning strategy for advisors and charitable clients | 0 | 13.68 | 06-07-2026 |
| 5 | New EITC Proposal Would Help Families Dealing with Rising Costs | 0 | 5.96 | 30-04-2026 |
| 6 | Некоторые россияне с 2027 года станут автоматически получать налоговые льготы | 2 | 6 | 21-07-2026 |
| 7 | 51.7M children qualify for Education Freedom Tax Credit | 0 | 7.49 | 28-07-2026 |
| 8 | Kinderfreibetrag soll 2027 um 300 Euro steigen | 0 | 14.26 | 07-08-2026 |
| 9 | Сумма маткапитала за двоих детей в 2027 году превысит 1 млн рублей | 0 | 0 | 29-09-2025 |
| 10 | Lawmaker introduces bill to expand EITC | 0 | 11.02 | 01-05-2026 |